What is an EMA crossover?
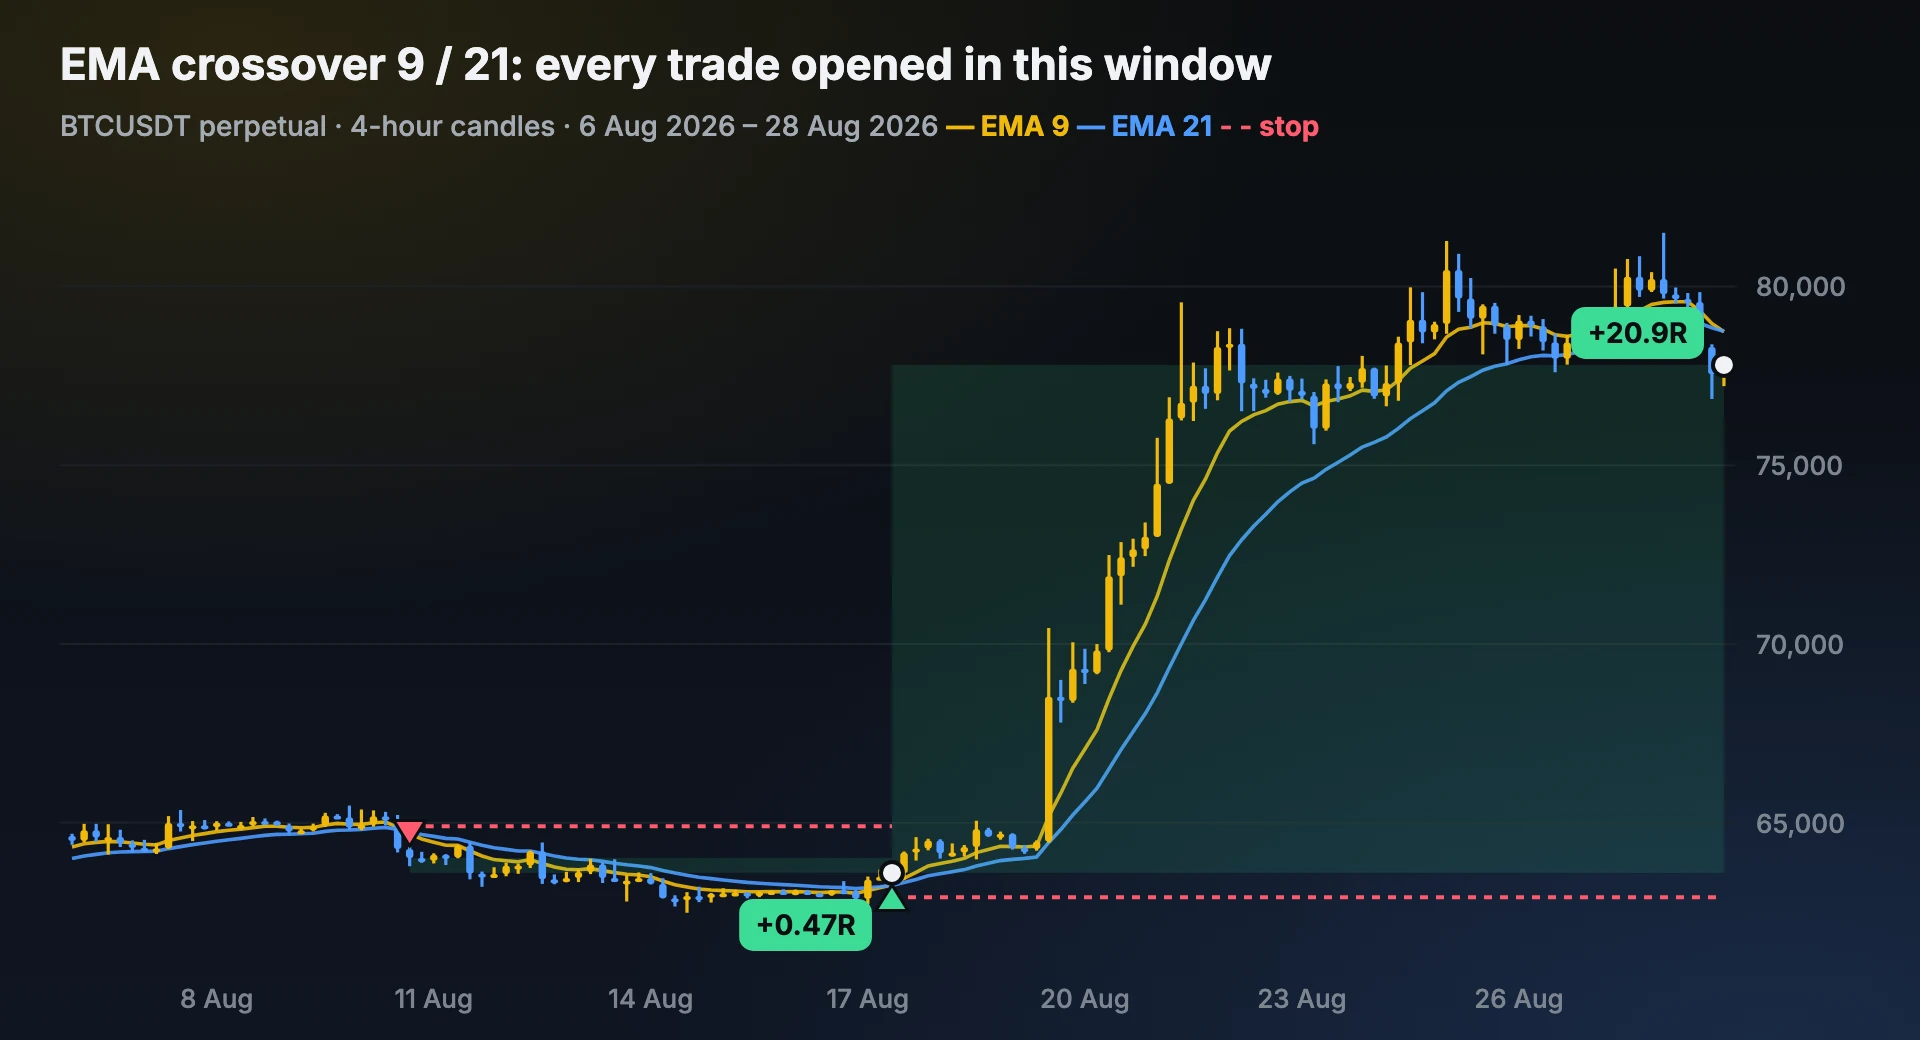
An exponential moving average (EMA) weights recent prices more than older ones, so it turns faster than a simple average. With a 9 EMA and a 21 EMA, the 9 follows the last few candles and the 21 the last few days of candles. When the 9 crosses above the 21, short-term momentum has turned up. Traders also use 20/50, 50/200 (see the golden cross) and many other pairs.
The rules we tested
- Long: at the close of the candle where EMA 9 crosses above EMA 21.
- Short: at the close where EMA 9 crosses below EMA 21.
- Exit: the opposite cross closes the trade and opens one the other way.
- Stop: 2 × ATR(14) from the entry, so every trade has a defined risk.
Results: six years, six coins, four timeframes
| Chart | Trades | Win rate | Average win | Average loss | Average R a trade | Max drawdown | Longest losing run | Years positive |
|---|---|---|---|---|---|---|---|---|
| 15 min | 57,846 | 22.4% | +2.03R | −0.78R | −0.15R | 8754R | 63 | 0 of 7 |
| 1 hour | 13,829 | 24.5% | +2.09R | −0.68R | 0.00R | 477R | 38 | 4 of 7 |
| 4 hours | 3,331 | 25.7% | +2.62R | −0.64R | +0.20R | 81R | 30 | 7 of 7 |
| 1 day | 501 | 30.7% | +4.44R | −0.66R | +0.91R | 24R | 19 | 6 of 7 |
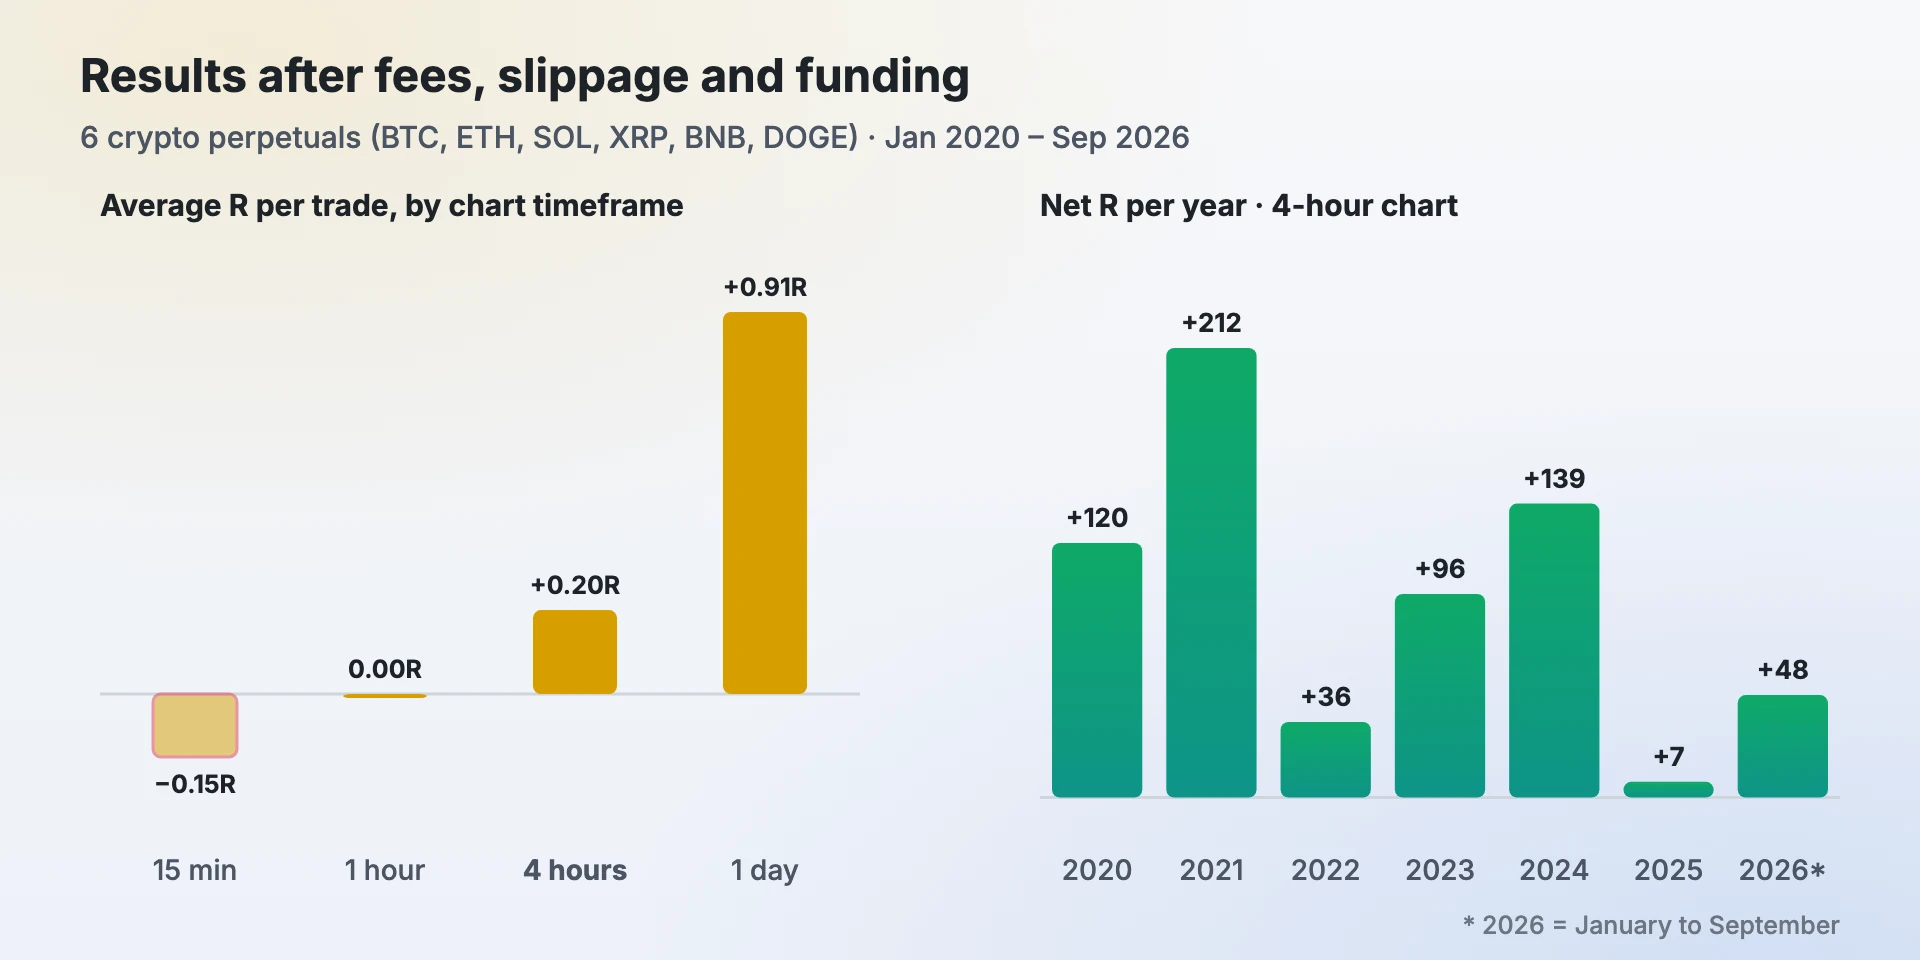
Per year on 4-hour charts: 2020 +120R · 2021 +212R · 2022 +36R · 2023 +96R · 2024 +139R · 2025 +7R · 2026* +48R. Per coin: BTC +0.23R · ETH +0.02R · SOL +0.20R · XRP +0.19R · BNB +0.25R · DOGE +0.32R.
| Chart | 2020–2023 | 2024 – Sep 2026 | Longs | Shorts | Coins positive |
|---|---|---|---|---|---|
| 1 hour | −0.02R | +0.02R | +0.05R | −0.06R | 3 of 6 |
| 4 hours | +0.25R | +0.13R | +0.42R | −0.03R | 6 of 6 |
| 1 day | +1.31R | +0.39R | +1.84R | −0.02R | 6 of 6 |
What the numbers say
- On 15-minute charts it lost every year. 57,846 trades, before costs +0.03R a trade, after costs −0.15R. The crosses are real but tiny, and fees and slippage are bigger. See how to backtest for the chart.
- 1-hour charts broke even; 4-hour and daily charts were positive on all six coins.
- Win rate was low on every timeframe: 25.7% on 4-hour charts. Most crosses are whipsaws in sideways markets; the trends pay for them.
- Longs again: +0.42R on longs, −0.03R on shorts on 4-hour charts.
- Losing runs: up to 30 losses in a row across six coins on 4-hour charts.
Crypto rose a lot between 2020 and 2026, so trend-following strategies earned most of their R on longs. A market that falls or goes sideways for years would give a different result. Past results don’t predict future ones.
Ways traders filter it
The plain crossover takes every cross, including the many in sideways markets. Common filters are trading only in the direction of a higher-timeframe trend (the filter that helped Donchian breakouts), skipping crosses when both EMAs are flat, or waiting for a pullback to the 21 EMA. We haven’t tested those versions here, so treat them as ideas to test, not results.
The rule vs your own judgement
A backtest measures the rule, not the trader. Most people who use an EMA crossover don’t follow it like a machine: they book part of the profit near a big level, skip a choppy day, or wait for a cleaner candle. That can make the result better or worse than the numbers above. On average it makes it worse: SEBI’s study of Indian F&O traders found that 93% of individual traders lost money over the three years to March 2024.
The way to find out which one you are is to measure it. Log every trade you take with this strategy under one strategy tag in your journal, note when you overrode the rule and why, and after 50 or more trades compare your average R with the rule’s. If your judgement adds R, keep it. If it costs R, follow the rule more closely. Our guide on how to journal trades shows what to record.
How to test it yourself
- Write the rules down exactly as above, or with your own changes.
- Open a chart with EMA 9 and EMA 21. In Profit Prism’s PPM Chart (included with every plan) it’s in the Indicators list, and Bar Replay lets you step through history one candle at a time without seeing what comes next.
- Take every signal the rules give, including the ones you don’t like, and record entry, stop, exit and R. Our free trading journal template does the maths.
- After 50–100 trades, compare your average R per trade with the table above, then read how to backtest a trading strategy for the mistakes to avoid.
How we tested it
- Markets: BTC, ETH, SOL, XRP, BNB and DOGE USDT perpetual futures (public exchange candles), each from its first candle; trades counted from 1 January 2020 to 30 September 2026.
- Rules: the textbook settings above, chosen before we saw any result and never tuned. One trade at a time per coin; a trade still open on 30 September 2026 isn’t counted.
- Fills: entries at the close of the signal candle. A stop is a stop order: it fills at the stop, or at the open if a candle gaps through it. If one candle touches both the stop and a target, we count the stop.
- Costs on every trade: 0.05% exchange fee and 0.02% slippage on each side, plus the real funding payments while the trade was open.
- Results in R: 1R is the distance from entry to the first stop, so a +2R trade made twice what it risked. This lets BTC at 60,000 and DOGE at 0.20 sit in one table.
- Two periods: 2020–2023 and January 2024 – September 2026, to see whether the result lasted.
The test code is ours and the data is public, so the numbers can be checked. This is crypto data only: we don’t have licensed NSE data, so treat Nifty and stock results as untested.
Frequently asked questions
What is the 9/21 EMA crossover strategy?
Buy when the 9-period exponential moving average crosses above the 21-period one, sell when it crosses below, and use the opposite cross to exit. It’s a simple trend-following strategy.
Does the EMA crossover strategy work?
In our six-year crypto test it lost on 15-minute charts (−0.15R a trade after costs), broke even on 1-hour charts and was positive on 4-hour (+0.20R) and daily charts. The timeframe mattered more than the rules.
Which EMA crossover is best for intraday trading?
In our test no 9/21 crossover made money on 15-minute charts after costs, because each cross earns less than fees and slippage take. If you trade intraday, check what costs are in R before choosing any crossover.
Is EMA better than SMA for crossovers?
An EMA reacts faster, so it signals earlier and gives more false signals. An SMA is slower and steadier. We tested EMA 9/21 and SMA 50/200; both worked best on 4-hour charts in our data.
What is the win rate of an EMA crossover?
About 25.7% on 4-hour charts in our test. Most crosses lose a little; a few catch trends worth many R.
See your own numbers
Profit Prism Journal measures every trade in R and shows your win rate, RR, leaks and loss limits — for crypto, forex, stocks and F&O. Try it free for 7 days, no card.
Start the free trialFor education only. Not investment advice. Trading involves substantial risk of loss.